One Month, One Table: What 30 Days of Real Returns Reveal About HSBC's ISA Funds Before 5 April
We ranked 30-day returns across HSBC's Global Strategy range, Vanguard LifeStrategy, gold ETCs and the defence sector in a single table. The spread tells a familiar story: short-term performance is a poor guide for picking ISA funds — but it's a useful one for checking what you already own.
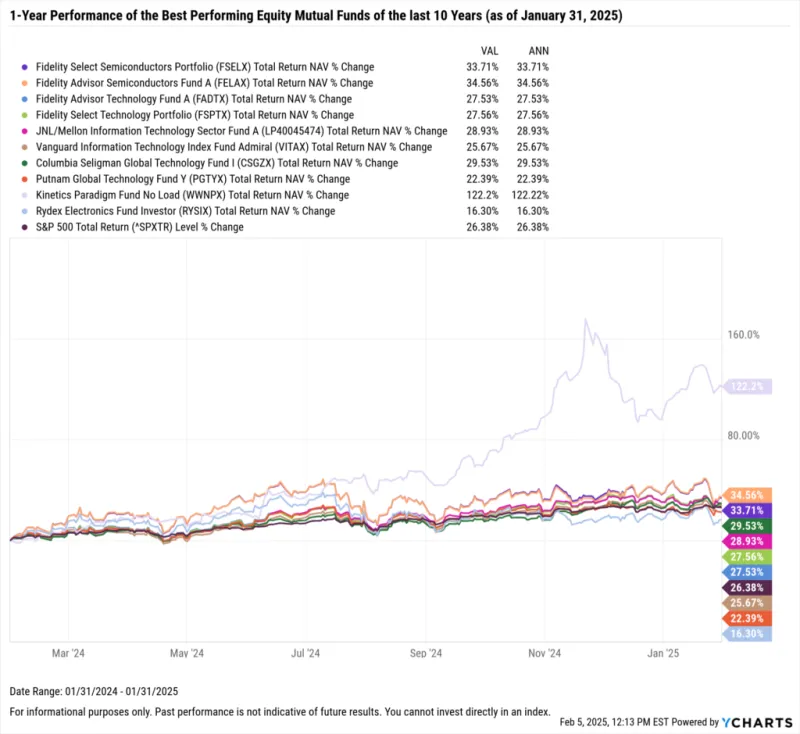
Days, Not Weeks: The Final-Fortnight ISA Checklist for the 5 April Deadline
The 2025/26 ISA allowance disappears on 5 April and does not roll over. Here is a risk-ranked action plan for using it in the final days — from topping up cash ISAs at the best easy-access rate to resisting the temptation of last-month's star performer.
The Dividend Timing Gap: Why FTSE 100 ISA Investors Are Leaving 2.1% Annual Returns Uncollected
For UK equity ISA holders, dividend income looks straightforward on paper. In practice, the gap between a stock's ex-dividend date and the actual cash landing in your account — combined with platform reinvestment delays — is silently compounding into a material annual return shortfall. For a £50,000 portfolio, the cost can exceed £1,000 per year.
The Hidden Cost of 'Free' Investing: How Platform Charges Are Quietly Eroding Your ISA Returns
Britain's most popular investment platforms advertise commission-free trading and no annual ISA fee. But beneath that marketing sits a different cost structure — one built on FX spreads, bid-ask markups, and cash drag — that can add up to 0.3% or more per year on a typical retail portfolio. We break down exactly where the money goes.
The £200 Tax Surprise: How Small Investment Gains Are Triggering Bills UK Investors Never Saw Coming
Thousands of UK retail investors believe gains under £1,000 are effectively tax-free. They are wrong — and the mechanics of CGT allowance interaction, platform reporting gaps, and self-assessment penalties are quietly turning modest wins into real losses. Here is exactly how it happens.
The Abandoned Portfolio: Millions of UK ISA Holders Are Still Paying for Fund Managers Their Advisers Quietly Stopped Believing In
When a financial adviser stops recommending a fund, they rarely tell their former clients. The result is that an estimated 2.3 million UK investors are still holding ISA funds that fell off approved lists years ago — often without knowing it, and almost always at a significant cost to their long-term returns.

The ISA Death Trap: Three Rules Executors Don't Know — and the Thousands Families Are Losing Because of It
When an ISA holder dies, their tax-free wrapper does not simply transfer to a beneficiary. A precise set of rules governs what happens next — and ignorance of the 36-month continuation window, the Additional Permitted Subscription mechanism, and platform-specific probate failures is costing British families thousands in avoidable tax every year.

Dormant ISA, Active Charges: How Platform Inactivity Fees Are Silently Draining British Investors' Wealth
Hundreds of thousands of UK investors leave ISAs untouched for years, assuming their money is simply sitting still. It is not. A network of inactivity fees, custody charges, and administration levies is quietly eroding those balances — and the damage over five years on a £50,000 portfolio is far larger than most people realise.

Pandemic Winners, Permanent Losers: The 40% ISA Drawdown Trap That 2.1 Million UK Investors Cannot Bring Themselves to Escape
Millions of UK ISA holders bought into the 2020–2021 bull market at peak valuations and are now sitting on losses exceeding 40%. The behavioural psychology of inaction, combined with a widespread misunderstanding of how ISA loss crystallisation actually works, is keeping billions of pounds locked in positions that the data suggests have no credible recovery timeline.
The SIPP Transfer Tax Ambush: Why Switching to a Cheaper Pension Platform Could Trigger an £8,000+ Bill You Never Saw Coming
Thousands of UK investors are transferring their Self-Invested Personal Pensions to lower-cost platforms in pursuit of fee savings — but a combination of transfer timing, illiquid asset valuation disputes, and poorly understood tax-loss harvesting rules is generating unexpected tax consequences that can dwarf the annual savings. Here is what the comparison sites do not tell you.
Vanguard LifeStrategy's Dirty Secret: The 0.8% Annual Gap That Costs Long-Term ISA Holders Thousands
Vanguard LifeStrategy funds are the default choice for millions of UK retail investors — but real-world return data reveals a persistent 0.8% annual shortfall against stated allocation targets. Platform drag, cash buffers, and rebalancing lag are compounding silently across decades of ISA contributions.
Dividend Reinvestment: The Setting That Looks Like a Shortcut But Quietly Erodes Your ISA Returns Over Time
Automatically reinvesting dividends inside an ISA sounds like effortless compounding — but platform-specific cash drag, settlement delays, and fractional share handling mean the reality can cost investors £1,200 or more over five years. We examine which reinvestment approach actually wins, and why the answer depends on your platform, your fund type, and your time horizon.
The Couples ISA Gap: How Sharing One Allowance Is Quietly Costing Married UK Investors £5,600 a Year
1.8 million married couples and civil partners are using only one ISA allowance between them, leaving up to £5,600 of annual tax-free investment capacity untouched. We map the most common planning errors, provide a step-by-step setup guide for single-earner and dual-earner households, and quantify the long-term wealth destruction this oversight creates.
Premium Bonds vs Cash ISAs: The £2,400 Annual Maths Gap That HMRC Cannot Touch
For 2.1 million British savers, Premium Bonds are quietly delivering better after-tax outcomes than Cash ISAs — but only for specific income profiles. We run the numbers, expose the misconceptions, and show exactly which saver should hold which product before the 5 April 2026 ISA deadline.
The 0% Credit Card Cash Flow Strategy: How Disciplined UK Investors Are Using Balance Transfer Windows to Fund Their ISA Before April's Deadline
With the ISA deadline on 5 April 2026 now days away, a growing cohort of financially literate UK households is deploying an unconventional tactic: using 0% balance transfer and purchase credit cards to free up cash flow, then redirecting that liquidity directly into Stocks and Shares ISAs or high-interest Cash ISAs. The maths can work — but only for those who understand exactly where the strategy breaks down.
The Hidden Pay Rise: How a Simple Workplace Benefits Audit Could Put an Extra £3,200 in Your Pocket This Year — Without Touching the Stock Market
Research consistently shows that the average UK employee fails to activate the full range of benefits their employer already funds — leaving a combined annual value of approximately £3,200 unclaimed. From unmatched pension contributions to salary sacrifice car schemes and sharesave plans, the financial gap hiding inside most employment contracts is larger than most people realise. Here is how to close it.
Pension Credit: The Free Government Top-Up Worth Up to £8,400 a Year That Millions of Retirees Simply Never Claim
Around 880,000 eligible UK pensioners are not claiming Pension Credit — leaving an estimated £1.7 billion in government support untouched every year. The average unclaimed entitlement is worth up to £8,400 annually. This is not a niche loophole; it is a mainstream benefit that the system has quietly failed to distribute.
The 13.8% Pay Rise Your Employer Is Keeping: How 3.4 Million UK Workers Can Reclaim Hidden Pension Savings Before the Tax Year Ends
Salary sacrifice pension contributions generate a National Insurance saving worth 13.8% of every pound redirected — but millions of UK workers never see this money because their employer retains it. With the new tax year beginning 6 April 2026, there is a narrow window to negotiate before contribution rates reset and the opportunity closes for another twelve months.
The £3,900 Pension Credit Ghost: Why 850,000 Eligible Pensioners Are Leaving Free Money on the Table Every Single Year
Pension Credit is one of the most valuable benefits available to low-income retirees in the UK, yet nearly one million eligible pensioners are not claiming it. Beyond the headline £3,900 annual gain lies a cascade of additional entitlements — from free TV licences to council tax reductions — that push the true annual value considerably higher.