Days, Not Weeks: The Final-Fortnight ISA Checklist for the 5 April Deadline
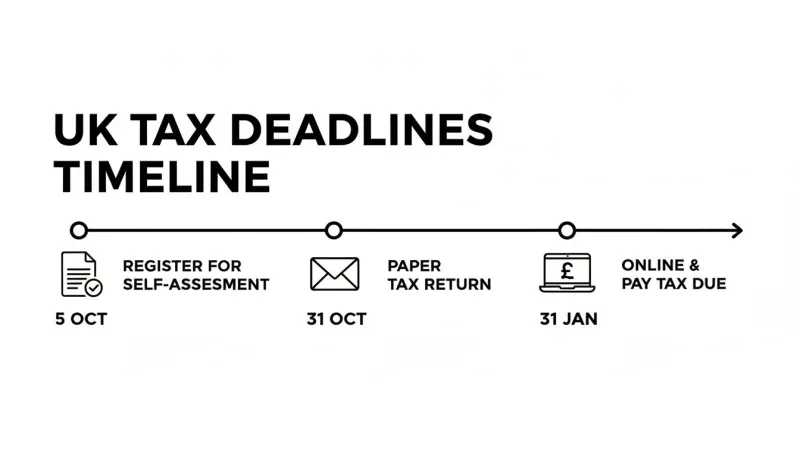
Photo: UK tax deadline calendar savings, via cdn.outrank.so
The clock is the story
On 5 April 2026, the £20,000 ISA allowance for this tax year expires. It does not carry forward. Every pound of that allowance left unused on 6 April is a tax shelter you can never claim back — and with the capital gains tax exemption now minimal, the value of sheltering investment growth inside an ISA has arguably never been clearer.
If you have done nothing yet, here is a plan for the final fortnight, sorted by how much risk you actually want to take.
Step one: know your number
Before anything else, check what you have already subscribed this tax year across all ISAs — cash, stocks and shares, Lifetime, Innovative Finance. The £20,000 limit is shared across all of them. Most banking apps show year-to-date subscriptions; if yours doesn't, check with each provider.
Step two: the risk-ranked checklist
Low risk / cash-first:
- Top up the best easy-access Cash ISA you can find — compare current rates on Moneyfacts or MoneySavingExpert rather than trusting your existing bank's loyalty rate
- If you can lock money away, fixed-rate ISAs typically pay more; check whether the term fits your plans
- Watch provider cut-off times: some banks require applications days before 5 April, not minutes
Medium risk / the balanced route:
- A Vanguard LifeStrategy fund (20%, 60% or 100% equity) via Vanguard UK or a low-cost platform gives instant diversification in one click
- Do not pick a fund based on the last 30 days of returns — our monthly comparison shows how wildly short-term rankings swing
- Transfer existing ISAs between platforms if fees are eating returns — but note that in-year transfers of the current year's subscription need care
Higher risk / equities:
- Global index trackers (iShares Core MSCI World, HSBC FTSE All World Index, Fidelity Index World) remain the default for long-term money
- Sector bets — defence ETFs, gold ETCs — are tactical, not foundational; if you want exposure, size it small
- Lump sum versus drip-feeding: investing a large amount days before a deadline is fine statistically, but splitting it over a few weeks is a legitimate comfort choice
Step three: check the cut-offs
Platform cut-offs for 5 April subscriptions vary:
- Vanguard UK, Trading 212, Freetrade: typically process until the deadline day, but fund settlement can slip — do not leave it to the evening of 5 April
- AJ Bell, Hargreaves Lansdown, Interactive Investor: publish specific ISA deadline guidance each March; read it
- Cash ISA providers: some require opening and funding several working days ahead
The single most common mistake is assuming the deadline is midnight on 5 April in every case. It frequently is not.
What not to do
- Do not chase last month's best performer — one month of returns is noise, as our 30-day comparison table shows
- Do not open a Lifetime ISA for money you might need before 60; the withdrawal penalty is punishing
- Do not forget your partner or spouse — two allowances mean £40,000 of shelter per household, and you can gift a spouse money to fund their ISA
What to watch in the next 30 days
- Any confirmation of ISA rule changes or allowance freezes in spring statements
- Cash ISA rate competition, which tends to sharpen in the final fortnight
- Market volatility around the tax-year end — deadlines are a poor reason to buy anything
Verdict
Use the allowance, match the product to your risk, mind the cut-offs — and let the deadline drive your timing, never your fund choice.
This article is for informational purposes only and does not constitute financial advice. Your capital is at risk. Past performance is not a reliable indicator of future results.